How Much Home Loan Can I Borrow

Ever wondered how much home loan you could borrow? It's like asking, "How many slices of pizza can I eat?" The answer depends on a bunch of factors, and it's actually pretty i...
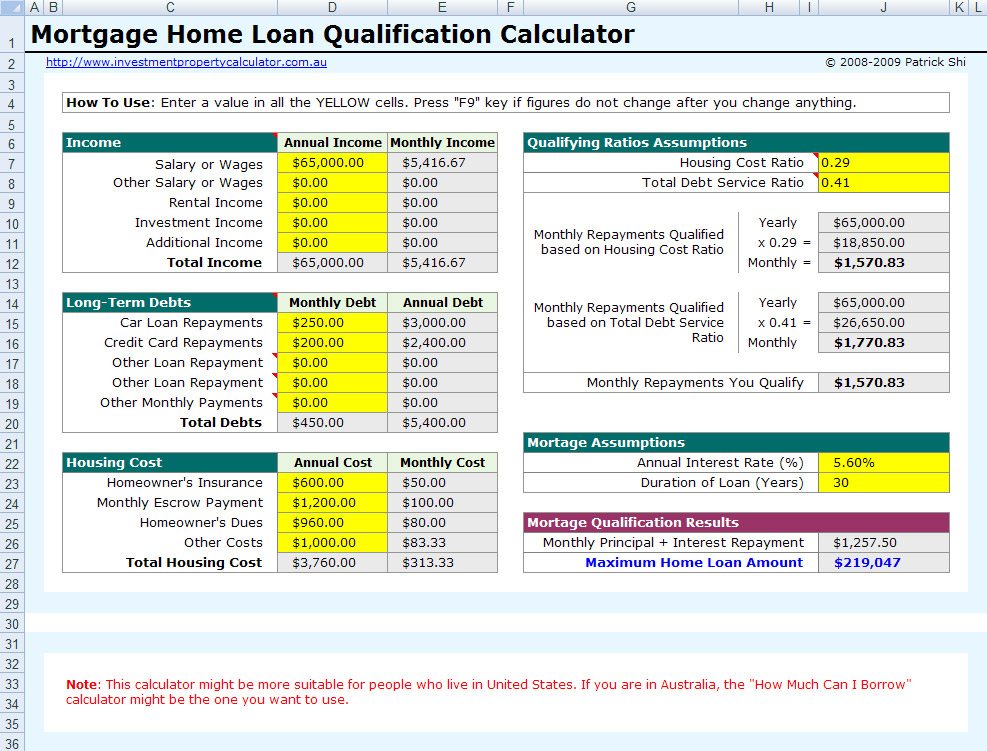
Ever wondered how much home loan you could borrow? It's like asking, "How many slices of pizza can I eat?" The answer depends on a bunch of factors, and it's actually pretty interesting to find out!
Your Magic Number: The Borrowing Capacity
First things first, let's talk about your borrowing capacity. This is the amount a lender thinks you can comfortably repay, based on your income, expenses, and credit history. It's like finding out how many slices of pizza you can afford without feeling sick afterwards!
But here's the thing, every lender has a different recipe for calculating this. Some might be more generous with the cheese (aka loan amount), while others might be more like, "Nope, you've already had enough."
Must Read
Income: The Main Ingredient
Your income is the star of the show when it comes to calculating your borrowing capacity. Lenders usually look at your gross income (that's before taxes), but they also consider how much you've got left after paying bills and other expenses.
Think of it like this: If you're earning $5000 a month, but you spend $3000 on rent, food, and other stuff, you've only got $2000 left to put towards a loan. So, that's what the lender will consider when calculating how much you can borrow.
Debt: The Spicy Pepperoni
Debt is like the spicy pepperoni on your pizza - it can add some heat, but too much can make things uncomfortable. Lenders look at your existing debts, like credit card balances or car loans, to see how much more you can take on.
For example, if you've got a $10,000 car loan and you're paying $200 a month, that's $2400 a year. A lender might subtract that from your annual income to see how much you've got left for a home loan.
Other Factors: The Secret Sauce
Income and debt are the main ingredients, but there are other factors that can affect your borrowing capacity. These are like the secret sauce that makes each lender's recipe unique.
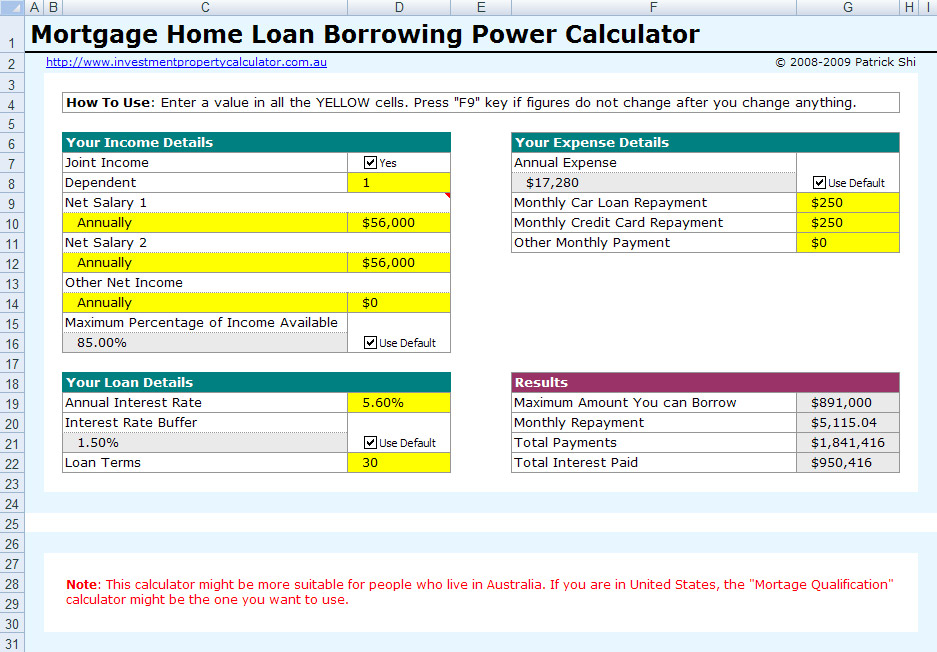 Free Mortgage How Much Can I Borrow Calculator
For instance, some lenders might consider your credit history. If you've got a history of making payments on time, they might be more likely to lend you money. But if you've had some late payments or defaults, they might be more cautious.
Other factors could include your age, the type of property you want to buy, and even the lender's current appetite for risk. It's a complex recipe, but it's all about finding out how much you can afford to borrow without stretching yourself too thin.
Why It's Cool to Know Your Borrowing Capacity
Knowing your borrowing capacity is like finding out how many slices of pizza you can eat without feeling sick. It helps you set realistic expectations about what you can afford. It's also a great way to start thinking about your financial future.
For example, if you know you can borrow up to $500,000, you can start looking at properties in that price range. But if you know you can only borrow $300,000, you might need to adjust your expectations or start saving more for a deposit.
Plus, knowing your borrowing capacity can help you negotiate with lenders. If you know you can borrow more than what they're offering, you might be able to negotiate a better deal.
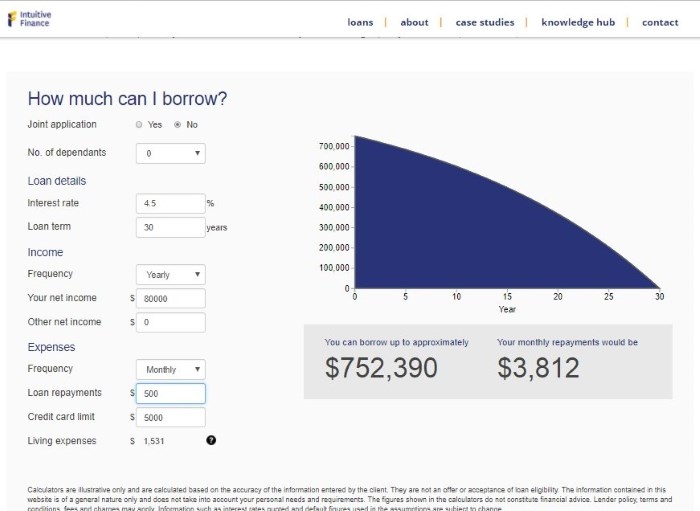 How Much Can I Borrow From Myjar? – MAMC
How to Find Out Your Borrowing Capacity
So, how do you find out your borrowing capacity? The good news is, it's not as complicated as it sounds. Here are a few steps you can take:
- Use an online calculator: There are plenty of online calculators that can give you a rough estimate of your borrowing capacity. They're not perfect, but they can give you a good starting point.
- Talk to a lender: Lenders are like the pizza chefs of the home loan world. They can give you a more accurate estimate of your borrowing capacity, based on their specific recipe.
- Check your credit score: Your credit score is like the secret sauce that can affect how much you can borrow. You can get a free copy of your credit report from each of the major credit bureaus once a year.
Remember, your borrowing capacity is just an estimate. The final amount you can borrow will depend on a lot of factors, including the lender's assessment of your application.
Don't Forget to Consider Other Costs
When you're thinking about how much you can borrow, it's important to consider more than just the loan amount. You'll also need to think about other costs, like stamp duty, legal fees, and ongoing expenses like rates and maintenance.
For example, if you're looking at a property that's $500,000, you might need to borrow $450,000 (assuming a 10% deposit). But you'll also need to factor in other costs, like stamp duty, which could be around $15,000 in some states. That's a lot of pizza!
So, How Much Can You Borrow?
The answer to that question is like the perfect slice of pizza - it depends on a lot of factors. But the good news is, it's not as complicated as it sounds. With a bit of research and some smart thinking, you can get a good idea of how much you can borrow.
And remember, it's always better to borrow a little less than you can afford, rather than stretching yourself too thin. After all, nobody wants to feel sick after eating too much pizza!
