Buying A House On Benefits Uk

Alright, mate, let's dive into this whole 'buying a house on benefits' thing, yeah? Grab a cuppa, get comfy, 'cause we're about to have a chat like we're old pals. First thin...
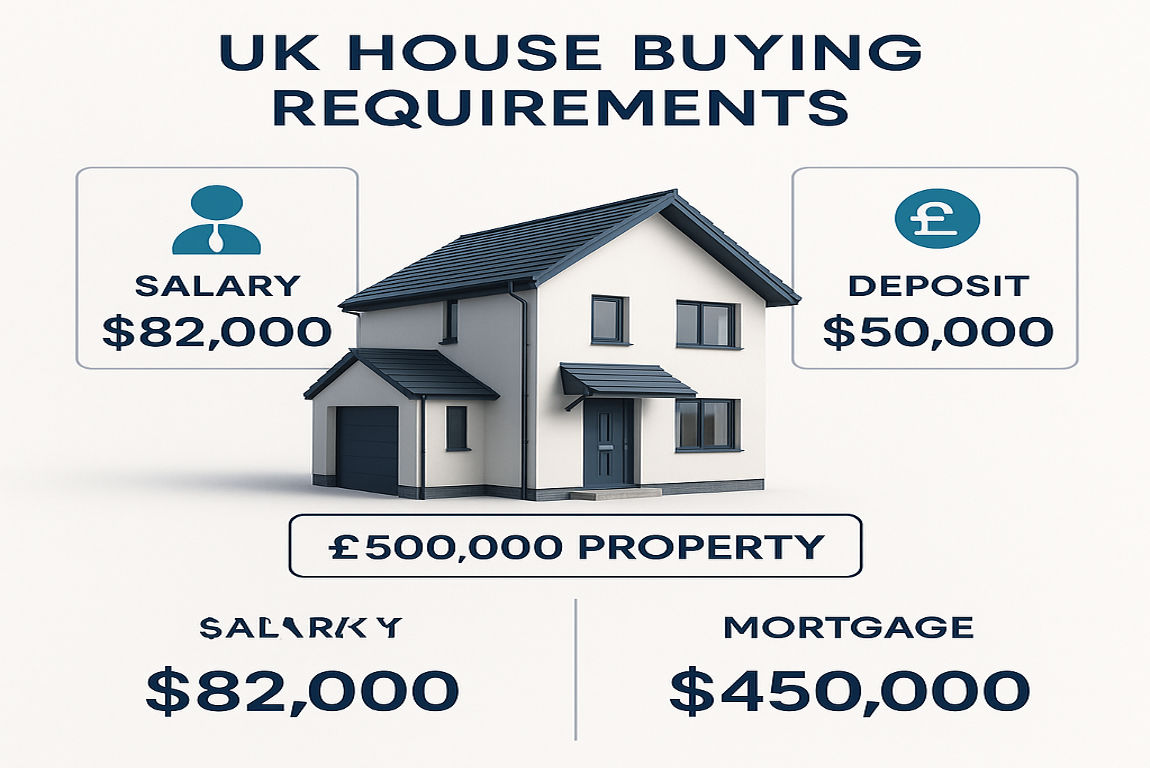
Alright, mate, let's dive into this whole 'buying a house on benefits' thing, yeah? Grab a cuppa, get comfy, 'cause we're about to have a chat like we're old pals.
First things first, let's talk money, honey!
You're on benefits, right? Well, good news! You can still get a mortgage. It's not like you're trying to buy a house with monopoly money (although, let's be real, that'd be awesome).
Now, lenders will look at your income, outgoings, and benefits. They want to make sure you can afford the mortgage. It's like when your mate borrows your car, but instead of checking they can drive, they're checking you can pay the bills.
Must Read
Some benefits count as income, like Income Support or Employment and Support Allowance. Universal Credit? Yep, that counts too. But remember, it's not just about what you get, it's about what you spend. So, keep those receipts, yeah?
How much can you borrow?
This is where it gets interesting. Lenders use something called an affordability calculator. It's like a magical mortgage crystal ball that tells them how much you can borrow.
They'll look at your income, outgoings, and then, ta-da!, they'll tell you how much you can afford. It's like when you're trying on shoes and the salesperson says, "These are your size, mate!" But instead of shoes, it's a house. And instead of your feet, it's your bank account.
 Inheriting a House While on Benefits UK - Speed Property Buyers
What about deposits and fees?
You might think, "I'm on benefits, I can't afford a deposit!" Well, hold your horses, partner. Some lenders only need 5% deposit. That's like ordering a small pizza instead of a large. You still get the house, just a bit less of it.
Fees? Yeah, they're a thing. Stamp duty, solicitor's fees, surveys... it's like going to the supermarket and suddenly remembering you need a bag for life. But don't worry, you can usually add these fees to your mortgage. It's like putting your shopping in the 'little bit more debt' aisle.
Shared Ownership and Help to Buy
Feeling like you're never gonna be able to afford a house? Well, hold onto your hats, 'cause here come the schemes!
Shared Ownership is like having a flatmate, but instead of them paying half the rent, they own a bit of the house. You buy a share (between 25% and 75%), and you pay rent on the rest. It's like buying a slice of pizza, but you still have to pay for the table.
 Is now a good time to buy a house? – The Subtle Investor
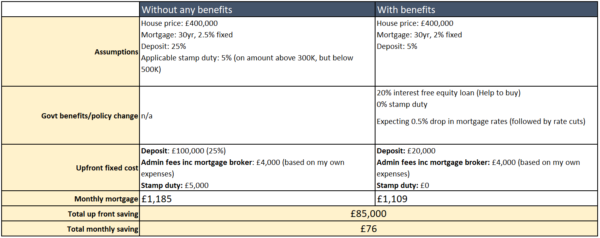
Help to Buy is like a government loan that helps you buy a house. You only need a 5% deposit, and they lend you up to 20% (or 40% in London) of the house price. It's like when your mate lends you £20 for a takeaway, but instead of a curry, you're getting a house.
So, can you really buy a house on benefits?
You betcha! It's not easy, and it's not quick, but it's definitely possible. It's like when you're trying to lose weight. You might not see results straight away, but if you stick with it, you'll get there in the end.
Remember, every lender is different. Some might say yes, some might say no. It's like dating. You might get rejected a few times, but then you meet someone who's perfect for you. And then you live happily ever after. Well, maybe not that happily ever after, but you get the idea.
So, chin up, mate. You can do this. You might not be able to afford a mansion, but you can afford a home. And that's something to smile about.
