Bond Yield To Maturity Formula

Alright folks, imagine you're at a big ol' garage sale, and you spot a shiny, new-looking bike. It's got a sticker on it that says, "Yield: 5% per year until 2030." Now, you'r...
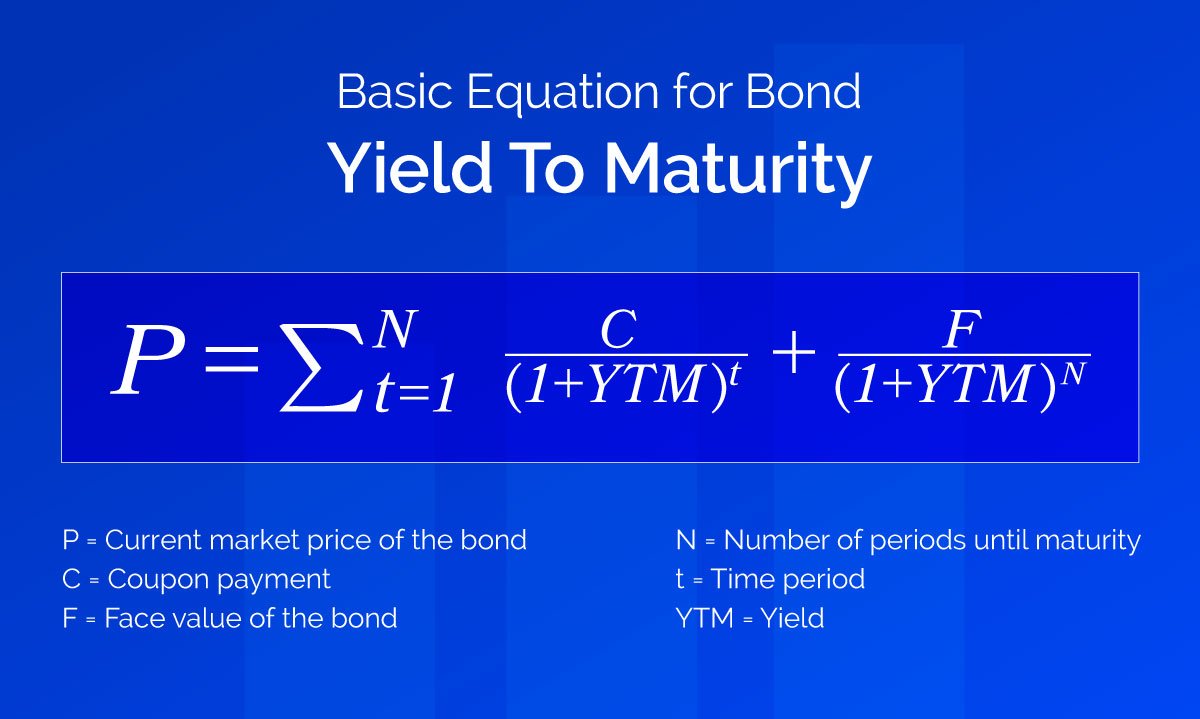
Alright folks, imagine you're at a big ol' garage sale, and you spot a shiny, new-looking bike. It's got a sticker on it that says, "Yield: 5% per year until 2030." Now, you're not a math whiz, but you're curious. How much money are you really gonna get from this bike every year?
That's where the Bond Yield to Maturity (YTM) formula comes in, like your friendly neighborhood calculator. It's not as scary as it sounds, promise. Let's break it down into bite-sized pieces.
What's a Bond, Anyway?
Think of a bond as an IOU from a company or government. They borrow money from you, and in return, they promise to pay you interest every year until the bond's lifespan is up. Then, they give you back your initial investment, called the face value or par value.
Must Read
So, that bike at the garage sale? It's like a bond. You buy it for $1000 (the face value), and every year, the seller gives you $50 (the yield) until 2030, when they give you back your $1000.
Now, Let's Talk Yield
Yield is just a fancy word for the interest you earn on your investment. It's usually expressed as a percentage of the face value. In our bike example, the yield is 5%.
But here's the thing: the yield you see on that sticker isn't always the yield you'll get. It's called the coupon rate, and it's based on the face value. But you might not buy the bond at face value. You could buy it for more or less, depending on the market.
 Yield to Maturity Calculator - Calculate YTM for Bonds - Inch Calculator
Enter Yield to Maturity
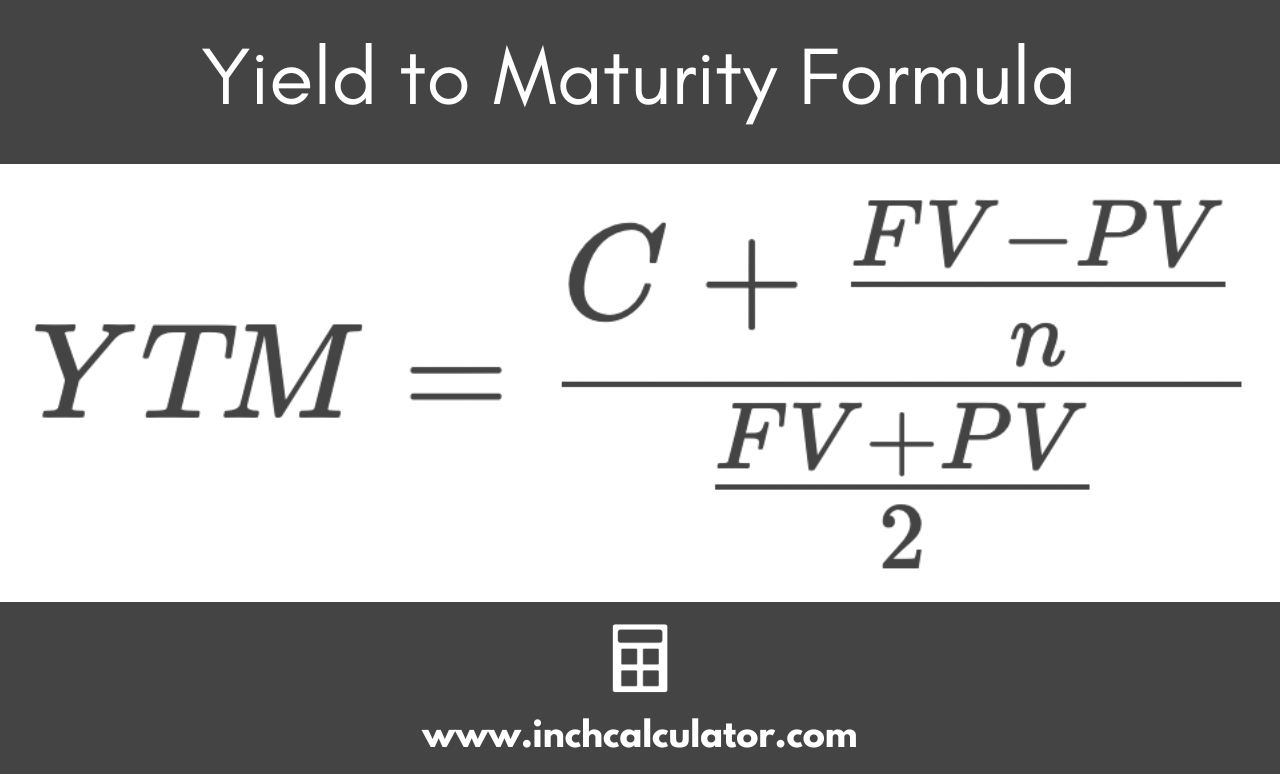
The YTM formula helps you figure out the real yield you'll get, based on the price you actually pay for the bond. It's like getting a more accurate estimate of how much money you'll get from that bike every year, depending on how much you paid for it.
Here's the formula in all its glory: YTM = (Annual Coupon Payment + (Face Value - Purchase Price) / Time to Maturity) / Purchase Price.
Don't let the symbols scare you. It's just a fancy way of saying, "How much money will you get every year, based on how much you paid for the bond?"
Let's Do the Math
Let's say you buy that bike for $800, not the face value of $1000. The annual coupon payment (the interest) is still $50, and the bike will be yours until 2030 (10 years).
 Bond Yield Maturity Calculator: Bond Yield Calculator – GSJWXX
Plug those numbers into the YTM formula, and you'll find that your real yield is about 6.25%, not the 5% you saw on the sticker. That's $50 every year, plus an extra $12.50, because you bought the bike for less than its face value.
Pretty neat, huh? It's like finding out you're gonna get more ice cream for your money at the ice cream truck. Now, you can make more informed decisions about whether that bike, or any other bond, is worth your cash.
But Wait, There's More
YTM assumes that you'll hold the bond until it matures (until 2030 in our bike example). But what if you sell it before then? That's where things get a tad more complicated, but we'll save that for another garage sale, er, article.
For now, you've got the basics down. You're now a bond yield to maturity pro, ready to navigate the wild world of garage sales and investments. Go forth, and may your yields be high and your bike rides be smooth!
