Alternatives To Buying A House Uk

Hey there, coffee in hand? Let's chat about something that's been on everyone's mind lately - alternatives to buying a house in the UK. I mean, who hasn't had that lightbulb m...
Hey there, coffee in hand? Let's chat about something that's been on everyone's mind lately - alternatives to buying a house in the UK. I mean, who hasn't had that lightbulb moment, "Hey, maybe I should stop throwing money at rent and actually own something!" But then reality hits, and you're like, "Whoa, how do I even start?"
Renting: The OG Alternative
Let's start with the obvious - renting. It's like dating before you're ready for a serious commitment. You get to try out different neighborhoods, and if it doesn't work out, you can always move on. Plus, no surprise maintenance bills, unless your landlord is a bit of a flake (but that's a story for another time).
But hey, if you're tired of your landlord's questionable decor choices and want something more permanent, stick around. We're about to dive into some alternatives that might just tickle your fancy.
Must Read
Shared Ownership: The Half-Commitment
Ever been in a relationship where you're just not ready to fully commit, but you're sick of the whole 'Netflix and chill' thing? That's kind of what shared ownership feels like. You buy a share of a property (usually between 25% and 75%) and pay rent on the rest. It's like dipping your toes into the homeownership pool without fully committing.
Sure, it's not the same as owning the whole place, but it's a step in the right direction. And who knows, maybe after a few years, you'll be ready to buy that remaining 25% and finally have the whole place to yourself (or with your partner, if that's your thing).
Help to Buy: The Government's Wingman
Now, imagine the government is your wingman, trying to set you up with a home. That's essentially what Help to Buy is. It's a scheme that helps you buy a new-build home with just a 5% deposit. The government then lends you up to 20% (or 40% in London) of the cost of the home, interest-free for the first five years.
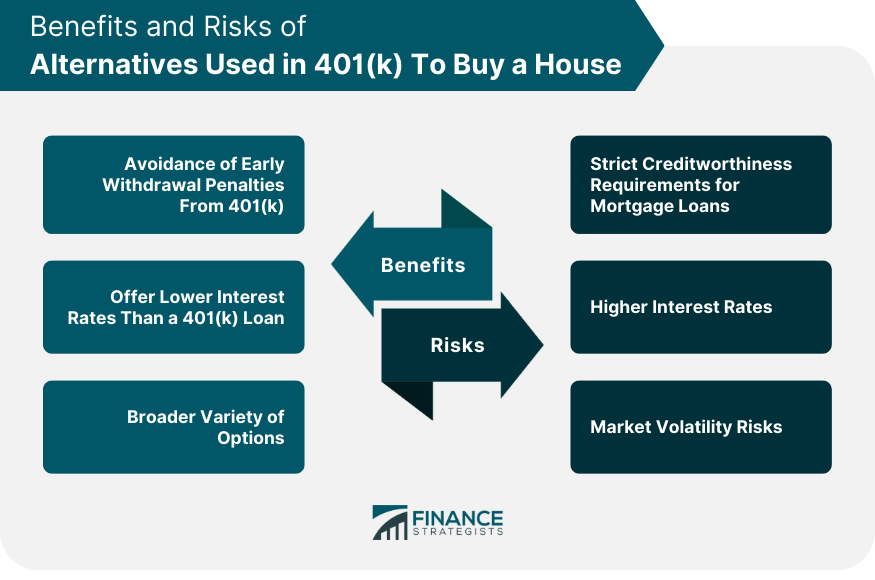 Alternatives to Using Your 401(k) To Buy a House
Sounds too good to be true, right? Well, there are a few catches. You'll need to have a mortgage for the rest of the property, and you'll have to pay a fee to the government when you sell your home. But hey, every wingman has their price, right?
Lifetime ISA: The Savvy Savings Account
Now, let's talk about the Lifetime ISA. It's like that friend who's always saving for a rainy day, but instead of being a total killjoy, they actually want you to join in. You can save up to £4,000 a year, and the government will add a 25% bonus to your savings. That's like finding a £1 coin on the street, but every year!
But here's the kicker - you can only use the money to buy your first home or for retirement. So, it's not like you can blow it all on a fancy holiday (not that we'd judge you, we've all been there).
 We Buy Any House Services: Pros, Cons, and 5 Alternatives
Co-op Homes: The Commune Life
Ever thought about living in a commune? No, not like the ones from the 60s with questionable hygiene standards. Co-op homes are a bit like that, but with a modern twist. You buy a share of a home (usually a flat) and become a member of a housing co-op.
You get to have a say in how the place is run, and you'll have to chip in with some of the maintenance. But in return, you get affordable rent and a sense of community. It's like living in a big, happy family (but hopefully not as dysfunctional).
So there you have it, folks. A few alternatives to buying a house in the UK. Each one has its pros and cons, and it's all about finding what works best for you. And hey, if you're still not sure, you can always just keep renting and treat yourself to that fancy coffee every now and then. You deserve it!
